Go straight to the topic
What is private liability insurance?
If you culpably cause damage to someone, you can be held liable. A legal basis is § 823 BGB. A serious injury can sometimes require years of treatment and care. The claim is not limited to the money you currently have in the account.
Your private liability insurance reviews such claims. It pays legitimate claims to the agreed extent and defends against unjustified ones. This passive legal protection is part of liability coverage. It does not replace a Legal expenses insurance, which you can use, for example, to pursue your own claims.
First check your current policy
In Germany, private liability insurance is generally voluntary. Before taking out a new policy, check whether you are insured through your family or partner. Get confirmation that the contract actually includes you.
Liability insurance: what is insured?
Whether the insurer pays in a specific case depends on your liability, the insured risk and the contract conditions.
Personal injury
You collide with a cyclist as a pedestrian. He gets injured. Treatment, pain and suffering, and loss of earnings may then be part of the claims. If the consequences are permanent, large sums may be involved.
Property damage
The knocked over glass from our example damages your friends' laptop. The necessary repairs or an appropriate replacement can be insured. There is no automatic entitlement to a brand new device.
Financial losses
After an injury or damage to property, further financial disadvantages can arise. Pure financial losses, which are not preceded by such damages, have their own conditions and compensation limits.
What is not automatically insured
If you drop your own laptop, this is not an ordinary liability case. Damage caused intentionally is excluded. Claims between people in the same contract can also be excluded. Professional or operational risks require a separate examination.
Damage caused while using a mandatory-insured car is generally covered by Car insurance. For your own belongings in the event of fire, burglary or water pipe damage, a Household contents insurance in question if the respective risk has been agreed.
How much does private liability insurance cost?
The cost of your private liability insurance depends, among other things, on who you insure, the coverage options you choose, and the amount of coverage and deductible. Depending on the provider, prior claims and other policy features may also play a role. Therefore, the price for a single-person policy says little about the premium for an entire family.
Compare the annual premium including insurance tax. Temporary discounts can make an entry-level price look cheaper; monthly payment may cost extra. You will receive a current premium via an offer with your details and the desired insurance start date.
With or without deductible?
With a deductible, you pay an agreed amount yourself in the event of a covered claim. This can lower the premium. You should calculate how much you actually save: even small annual savings can be wiped out by just one claim.
Only choose a deductible high enough that you can pay it from your savings in the short term. Further claims may change the bill again.
Understand your deductible in more detail- Excess
- 150 euros
- Contribution savings per year
- 20 euros
7.5 yearsPremium savings for a full deductible
150 divided by 20 gives 7,5. The invoice assumes damage in which you are responsible for the full 150 euros yourself. Further damage is not included.
Comparing personal liability insurance: What matters?
Compare the benefits first, then the premium. Use the same insured persons and the same deductible as the basis for the offers. Otherwise, different contracts will be compared side by side, even if the tariff names sound similar.
- Sum insured
- The consumer advice center recommends at least 10 million euros Flat rate for personal injury, property damage and financial loss. This is not a legal minimum requirement. Also look for higher amounts and limits per person injured.
- Individual limits
- Loss of keys, damage to rental property or borrowed items may have lower limits than the large coverage amount on the first page. Read these positions individually, including exclusions.
- Insured persons
- Partner and children must be covered by the contract. The rules are relevant when moving in together, during training and after a separation.
- Your everyday life
- Young children, help with moving, private stays abroad: The clauses on children not liable for damages, courtesy damages, and international coverage are relevant here. Volunteering, renting out property, or special hobbies may raise further questions.
- Cover for unrecoverable claims
- If someone causes you damage, is liable for it and cannot pay, this clause can help. There are specific requirements for this, such as enforcing the claim, minimum damages and proof of insolvency. This means that your own mishaps are not generally insured.
- Term and claims service
- When can you cancel, how do you report damage and what evidence is required? Write down any unclear points where they were found in the contract. In this way, a specific question can be clarified.
Liability insurance for singles, couples and families
A single tariff generally protects the insured individual. Couples and families can choose a joint contract. This can be cheaper than several individual contracts as long as all the people required are included.
Living together alone is not sufficient proof. Whether a shared household is required and how an unmarried partner must be named is stated in the conditions.
Children can also be insured during training or studies. When it comes to adult children, it's worth taking a closer look: What applies to interruptions, further training or starting a career? A general age limit does not answer this. Report relevant changes and confirm who is currently insured.
Pay attention to the clause for small children
Parents are not automatically liable for every loss caused by their child. Under § 828 BGB, children under seven are generally not personally liable. Additional rules apply to children aged seven to under ten in certain traffic accidents; for older minors, their ability to understand also matters. Parents may themselves be liable if they breach their duty of supervision (§ 832 BGB).
If neither the child nor a parent is liable, normal liability coverage does not have to provide compensation. A clause for children who are incapable of committing a crime can still cover such damage. Read the maximum amounts and requirements in the contract.
Damage to rental property and loss of keys
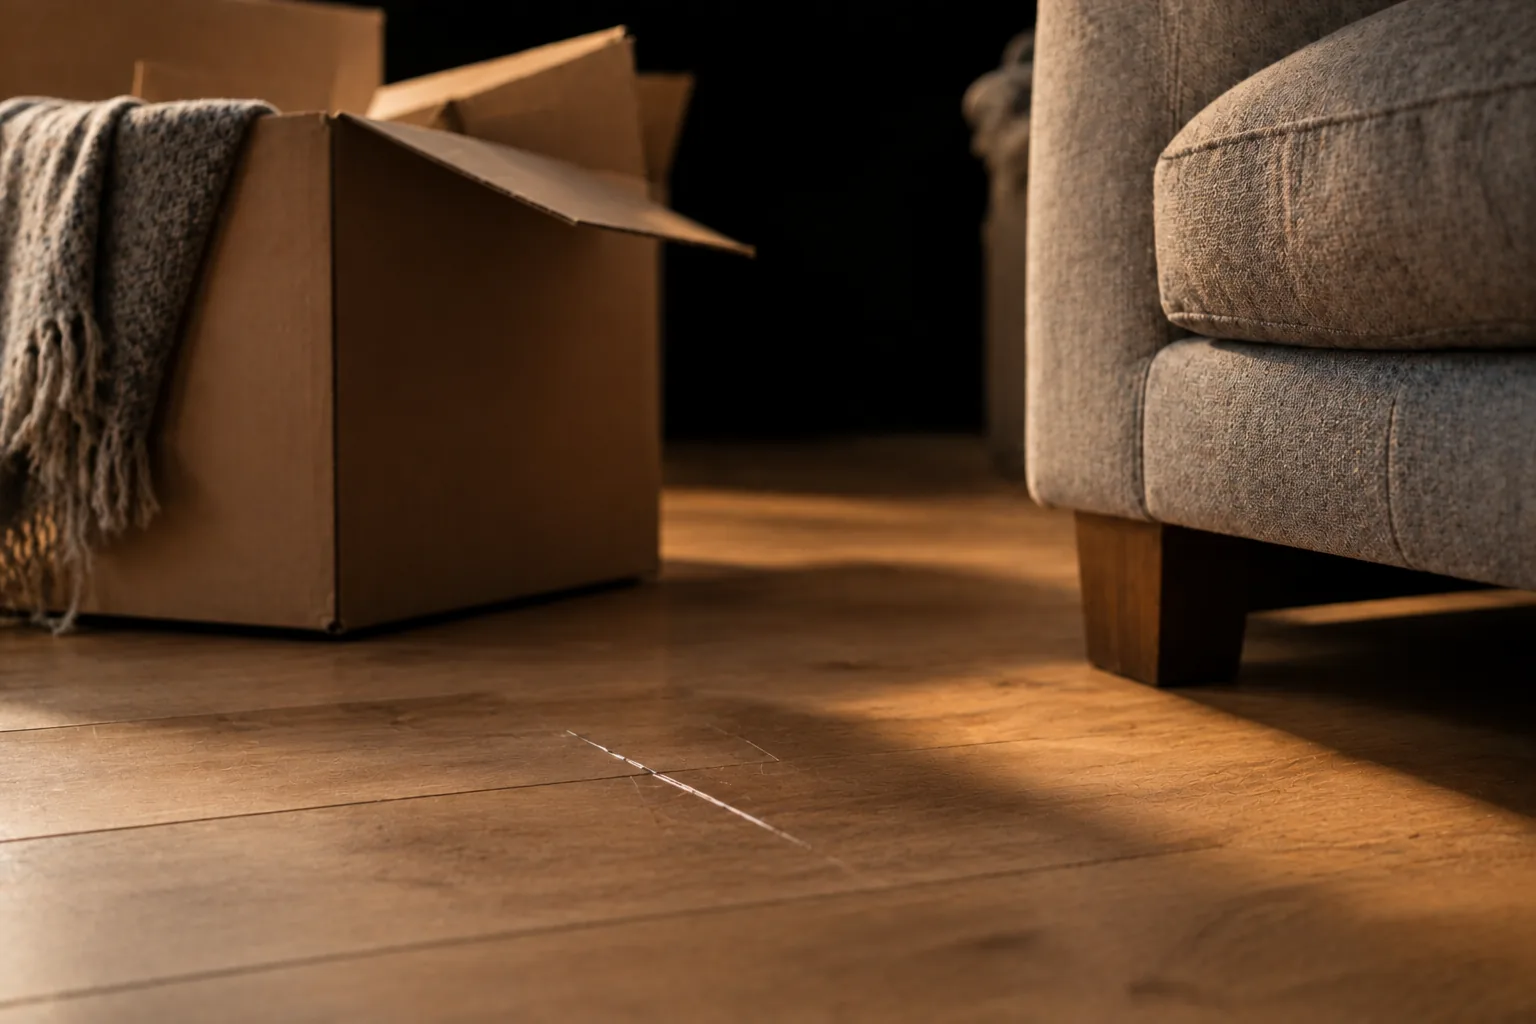
Damage to rented parquet: The cause and the contractual conditions matter.
Damage to rented premises
If you accidentally damage the flooring in your rented apartment, the rental property damage coverage may apply if rented living spaces are included. Normal wear and tear is excluded. Glass, excessive use, or built-in fixtures may have different terms or exclusions.
Rented furniture and borrowed tools are not automatically covered. Separate clauses apply to movable property. For holiday apartments and hotel rooms, it also depends on which items, causes of damage and compensation limits are covered by the contract.
A lost key can affect the entire locking system.
Apartment and work keys
If a third‑party key is lost, a duplicate is not always sufficient. In some cases, the entire locking system may need to be replaced. The contract should clearly stipulate coverage for third‑party private and professional keys, the maximum limit, and any additional deductible. Access cards and transponders may have their own rules.
A lost key clause does not cover every lock replacement. The insurer will assess whether you are at fault and whether the costs are justified. You must check your policy separately to confirm if consequential damages are included.
A claim has occurred. Here is how you report it.
Report the damage to your insurer immediately. You don't need to determine beforehand who is legally responsible. Verifying claims is part of their job.
- Limit further damage
Do what you can safely to prevent the damage from getting worse.
- Take photos and notes
Record the date, location, people involved and what happened. Keep existing receipts.
- Inform the insurer
Use the designated reporting channel and adhere to the contractual deadlines.
- Forward claims
Also send legal letters promptly. Don't let set deadlines pass.
- Reconcile payments and commitments
Speak to your insurer before paying or making a binding commitment. Answer follow-up questions fully.
Photos and notes help when reporting a claim.
Submitting the claim does not yet confirm coverage of costs. Keep the documents and follow up if a decision remains unclear.
Frequently asked questions about personal liability
Is private liability insurance mandatory in Germany?
No. There is no general legal obligation to take out insurance in Germany. You can still be liable for damage caused by negligence, even without insurance. Different rules apply for specific risks, such as when using a vehicle that is subject to compulsory insurance.
Does private liability insurance also apply abroad?
Many tariffs also apply during a temporary private stay abroad. The conditions state the insured countries, the permitted duration and the requirements for your place of residence. A vacation in Poland is different than a permanent move there. Clarify longer stays with the insurer before departure.
Are dogs and horses insured under private liability insurance?
Own dogs and horses are usually not included in basic protection. Pet owner liability insurance is an option for them. Tame small animals such as cats are often covered. If you occasionally look after someone else's animal, check what your contract says about this.
Does new liability insurance pay for old damage?
A new contract does not retroactively insure damage that has already occurred. The agreed start of insurance and the conditions are decisive. If you only notice previous damage after the change, use the time of damage to clarify with the insurers involved who is responsible.
When can I cancel or change my personal liability insurance?
The term and notice period are stated in your contract. There is often a three-month notice period before the end of the contract. Following a premium increase or a claim, special termination may be possible under certain conditions. Pay attention to when the cancellation must be received by the insurer and ensure the new protection starts without any gaps.
Sources and Context
Content version: . The linked laws and consumer information explain the basics. The specific insurance terms apply to your cover; your individual case must be assessed separately.
- Consumer advice center: Private liability insurance and important contractual services (opens in a new tab)
- § 823 BGB: Obligation to pay damages (opens in a new tab)
- § 100 VVG: Benefits provided by the liability insurer (opens in a new tab)
- § 828 BGB: Liability of minors (opens in a new tab)
- § 832 BGB: Liability for violation of the duty of supervision (opens in a new tab)
The publisher is Praedurion. Provider and register information is available in Legal notice.
General information. Whether and to what extent a contract suits you must be assessed individually. This information page does not calculate premiums and does not offer insurance contracts.